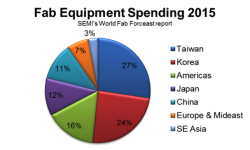
SEMI, San Jose, Calif., has published its May update to the World Fab Forecast, reporting on more than 200 facilities with equipment spending in 2015, and more than 175 facilities projected to spend in 2016. Semiconductor industry capital expenditures (without fabless and backend) are expected to slow in rate, but continue to grow by 5.8% in 2015 and 2.5% in 2016.
Fab equipment spending is forecast to depart from the typical historic trend over the past 15 years of two years of spending growth followed by one year of decline. Departing from the norm, equipment spending could grow every year for three years in a row: 2014, 2015, and 2016.
The report shows a large increase in spending for DRAM, more than 45% in 2015. Also, spending for 3D NAND is expected to increase by more than 60% in 2015 and more than 70% in 2016. The foundry sector is forecast to show 10 percent higher fab equipment spending in 2015, but may experience a decline in 2016. Even with this slowdown, the foundry sector is expected to be the second largest in equipment spending, surpassed only by spending in the memory sector.
A weak first quarter of 2015 has dropped spending for the first half of 2015, but a stronger second half of 2015 is expected. Intel and TSMC reduced their capital expenditure plans for 2015, while other companies, especially memory, are expected to increase their spending.