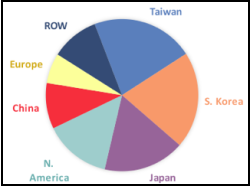
IC Insights, Scottsdale, Ariz., recently released its new Global Wafer Capacity 2016-2020 report showing that, as of December 2015, Taiwan is now the global leader in wafer capacity with nearly 22% of worldwide IC capacity installed in the country. Taiwan surpassed South Korea in 2015 to become the largest capacity holder, after having passed Japan in 2011. China became a larger wafer capacity holder than Europe for the first time in 2010.
The report provides in-depth detail, analyses, and forecasts for IC industry capacity by wafer size, by process geometry, by region, and by product type through 2020. The graph shows the world’s installed monthly wafer production capacity by geographic region (or country) as of December 2015.
For wafers 150mm in diameter and smaller, Japan was the top region in terms of the amount of capacity. The fabs running small size wafers tend to be older and typically process low-complexity, commodity-type products or specialized devices.
The capacity leaders for 200mm wafers were Taiwan and Japan. There have been many 200mm fabs closed over the past several years, but not in Taiwan, and that resulted in the country becoming the largest source of 200mm capacity beginning in 2012. With Taiwan home to most of the IC industry’s foundry capacity, the country’s share of 200mm capacity will likely rise further in the coming years.
For 300mm wafers, South Korea was at the forefront, followed by Taiwan, which lost its position as the leading supplier of 300mm wafer capacity in 2013. That was in large part because ProMOS closed its large 300mm fabs, but it was also due to Samsung and SK Hynix continuing to expand their fabs in South Korea to support their high-volume DRAM and flash businesses.